Wander — Diligence Pack
Wander is a UAE movable-camp and glamping operator with a real track record — repeat brand-name clients (Laureus, INEOS, KTM, BMW, Emirates NBD) won on word of mouth, with no marketing.
The financials show three seasons of ~AED 0.6m, ~1.4m and ~0.7m (peak in Year 2; booked ~1.8m before flood cancellations) — but the only real monthly accounts, the actual P&L for Oct 23–Mar 24, ran at ~28% net in a fixed-venue model, not the ~50% the forward model projects; one delivered event P&L confirms where the margin really lives (teepees ~86%, F&B ~71%). A fire then damaged the kitchen-deck containers and closed the camp early, and the kit is now being auctioned as a job-lot — Vren bidding ~AED 90k against a ~130k estimate. The live pipeline is real but uncontracted: the LinkViva 200-tent festival RFP, plus warm repeat clients (Absolute Adventures, GoToDXB).
The upside is the go-to-market: a business that already wins repeat enterprise demand on zero marketing, wrapped in a marketing engine. A grounded realistic Season 1 lands at ~AED 1.0m and ~22% net — a lift on history, not the model's 50-event run-rate. The next moves are planned: the named-buyer list build plan and the TAM sizing plan. Read the key assumptions first — they are what an investor tests. Every source file sits in the right-hand panel.
Reconciled financials
Three trading seasons — AED 597k → ~1.4m → 748k — peaking in Year 2 at ~AED 1.4m, each run solo and cut short. The memo's 748k is Season 3 (588k booked + a 160k illustrative walk-in/bar/truck estimate, shown separately, never summed).
| Season 1 (22/23) | Season 2 (23/24) | Season 3 (24/25) | |
|---|---|---|---|
| Recorded revenue | AED 597,063 | ~AED 1,383,000 | AED 588,179 |
| Make-up | Vivid Events (pre-investment) | Vren/Wander ~1.07m + Oliver/HO/TS ~0.31m | Own invoicing (#3003–3031) |
| Scope | Pop-ups & school camps, solo | Booked ~1.8m; flood cancellations | Booked events; +160k est. → 748k |
| Disrupted by | — | Late financing (~2-mo late open) + flood (early end) | Late financing (~2-mo late open) + fire (early end) |
Three revenue channels (they sum)
(1) Vren's camp invoices (~AED 1.07m, S2); (2) cash + POS — missing from the sheets; (3) Oliver's Terra Solis invoices (~0.31m, S2). So recorded ~1.4m understates the truth (bookings ~1.8m). Action: one ledger + recover the POS cash.
Event P&L — Organic Lifestyle retreat (Showka, 15–17 Nov)
The one full P&L in the pack — a single event, end to end.
| Line | AED |
|---|---|
| Total sales & other income | 66,345 |
| F&B cost | (7,339) |
| Activities & entertainment (drumming, hiking, etc.) | (11,250) |
| Teepee cost | (2,625) |
| Operations — staff | (7,500) |
| Operations — diesel | (2,500) |
| Operations — water | (600) |
| Total event cost | (31,814) |
| Event net profit | 34,531 — 52% |
Margin by line — where the money actually is
| Line | Income (AED) | Cost (AED) | Margin | % |
|---|---|---|---|---|
| Teepees (35 × 520) | 18,200 | 2,625 | 15,575 | 86% |
| F&B + beverage | 25,650 | 7,339 | 18,311 | 71% |
| Paid activities (drumming, entertainment, hiking) | 14,600 | 11,250 | 3,350 | 23% |
| Yoga, henna, transfers | 7,895 | 0* | 7,895* | *cost blank |
| Operations (staff 7,500 · diesel 2,500 · water 600) | — | 10,600 | (10,600) | direct opex |
| Event net | 66,345 | 31,814 | 34,531 | 52% |
The margin engine is teepees (~86%) and F&B (~71%) — the owned asset plus catering. Bought-in activities run only ~23% and mostly pad the top line. Yoga, henna and all transfers show zero cost (blank, not free), so the headline 52% is flattered — fill those and net falls.
Actual monthly P&L (Oct 2023 – Mar 2024)
The only real month-by-month accounts in the pack (P&L 2024.xlsx) — WANDER RETREATS run as a fixed RAK venue + F&B / "Holiday Home" (restaurant, bar, rooms, RAK destination fee), not the mobile-events model the forecast assumes.
| Month | Income | Gross profit | Net profit | Net % |
|---|---|---|---|---|
| Oct 23 | 14,204 | 3,837 | (56,445) | open / loss |
| Nov 23 | 123,754 | 117,221 | 20,616 | 17% |
| Dec 23 | 175,636 | 155,654 | 77,946 | 44% |
| Jan 24 | 79,030 | 76,316 | 5,486 | 7% |
| Feb 24 | 156,070 | 155,230 | 91,985 | 59% |
| Mar 24 | 102,797 | 102,403 | 44,848 | 44% |
| 6-month total | 651,491 | — | 184,436 | 28% |
These venue accounts were compiled by Terra Solis as an audit attempt and are incomplete — POS-tied cash isn't in the held copies, so revenue is likely understated. Feb 2025 had fallen to ~AED 29k (vs AED 156k a year earlier), consistent with the late start / flood / fire disruption. RAK licensing confirmed by the destination-fee report (Holiday Home category).
Key assumptions (the three that decide the raise)
What an investor will test first
1 · The 160k estimate. Stop summing it into the 748k headline — it's the single most attackable number.
2 · The fire. A core asset (kitchen deck) is down and the going-concern status is unstated. Silence reads as risk.
3 · One ledger. Two parallel records of the same revenue must be reconciled before anyone outside sees both.
Full register: 20+ assumptions across revenue, margin, assets, model and pipeline — held in the vault (assumptions-register.md).
Asset register & valuation
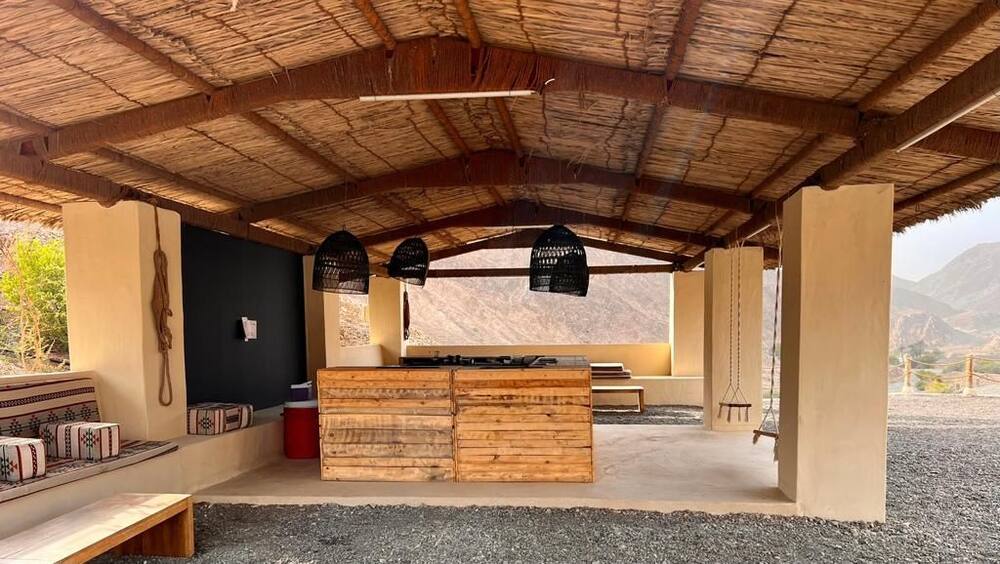
The physical kit, extracted from the WANDER deck and reconciled against the auction bid grid (06-20 meeting). Two groups: the camp job-lot the landlord is auctioning (sold as seen) and kit owned by Vren (not in the auction). Items the deck flagged "TO BE VERIFIED" are marked TBV. Figures operator-supplied.
Camp job-lot — the auction
| Item | Detail | Qty | Condition | Orig cost (AED) | Auction bid (AED) |
|---|---|---|---|---|---|
| Teepee frames | Vren-designed — holds the IP + Pakistan manufacturing contract; covers all need replacing ~$900 ea | 38 (2 need repair) | frames good; covers damaged | ~800 ea to build | 2,880 (36×80) |
| Container bathroom — male | 2 toilets · 3 urinals · 4 showers · vanity, 3 sinks | 1 | good (~20 nights); 60k offered for the pair, refused | 105,000 | 25,000 |
| Container bathroom — female | 4 toilets · 4 showers · vanity, 3 sinks | 1 | good (~20 nights) | 110,000 | 25,000 |
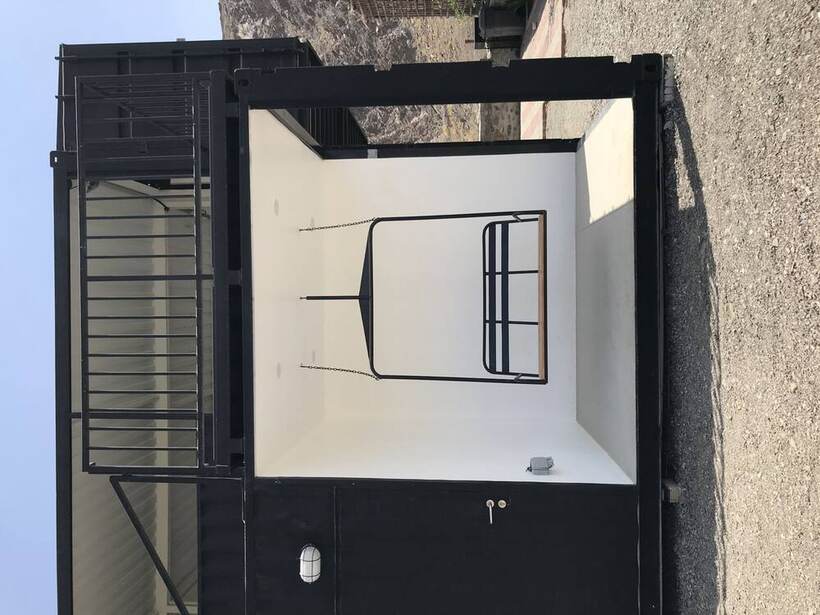
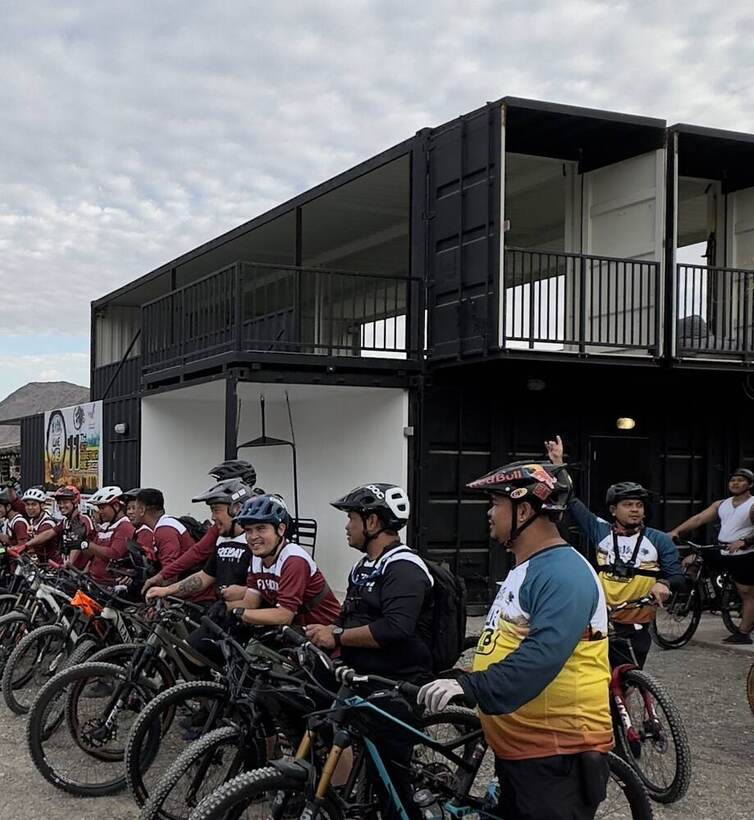
| Kitchen top-deck unit | 3×40ft lower + stairs container + 3 top-deck containers, Juliet balconies, insulated, water + power | 1 | fire-damaged — needs rewiring + repaint | — | 15,000 (kitchen items) |
| Staff accommodation | 40ft, 4 A/C cabins, 1 bathroom | 1 | — | — | 10,000 |
| Storage container | 40ft, power + A/C, insulated | 1 | — | — | 5,000 |
| Mattresses & linens | bedding for ≥100 pax (TBV) | ~105 | TBV | — | 5,250 (105×50) |
| Misc — furniture / linens | oil-barrel tables, glassware, etc (TBV) | — | TBV | — | 10,000 |
| Pallets, fairy lights, benches | — | — | — | — | 1,000 |
| Bar | pallet bar 6pcs, marble top, back bar w/ sink, glassware, barrel tables, under-bar fridge (TBV) | 1 | TBV | — | in misc / kitchen |
| Subtotal | 99,130 | ||||
| Pool | must be cut in half to remove | 1 | scrap | — | 10,000 |
| Café unit | — | 1 | scrap | — | 35,000 |
| Scrap subtotal | 45,000 | ||||
| Total (indicative) | original cost stated "over AED 1.2m" | 144,130 |
Owned by Vren — not in the auction lot
| Item | Detail | Notes |
|---|---|---|
| Food truck | SS sink/worktop, 2 counters, coffee machine + grinder, under-counter fridge, microwave, 2 kettles, double-tier pizza machine | new registration |
| Portable toilet/shower units | M: 4 toilets, 4 showers · F: 4 toilets, 4 showers | Vren-owned (separate from camp bathrooms) |
| Reception container | 30ft open + 20ft verandah, CCTV monitor | Vren-owned |
| Trailer | 5 × 2.2 m | unregistered |
| Oil tanker / bike rack | — | possibly available |
| Security cabin | — | possibly available |
Source: deck PDF · WANDER ASSETS .pptx · bid grid from the 06-20 auction meeting note.
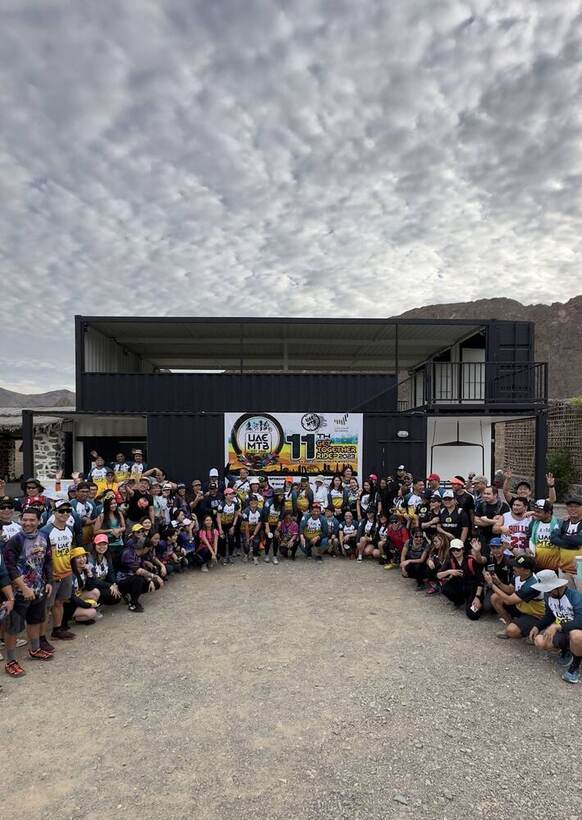
Photos — the kit being sold
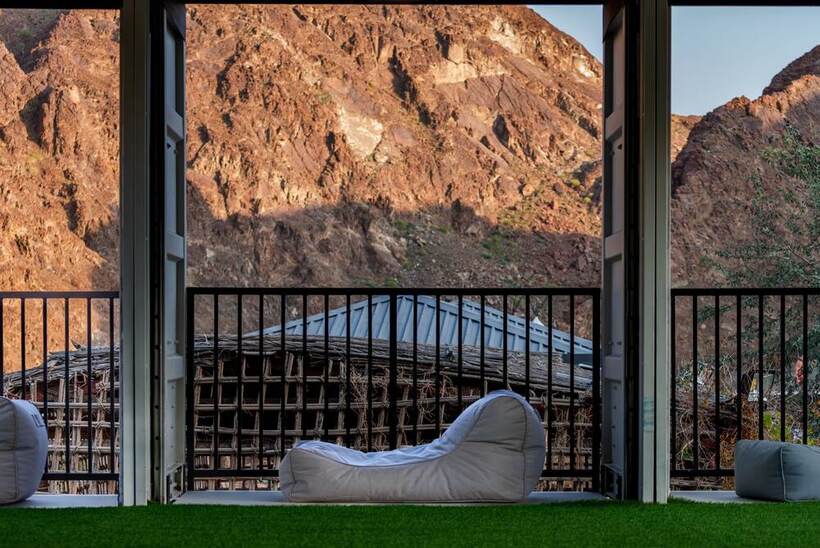
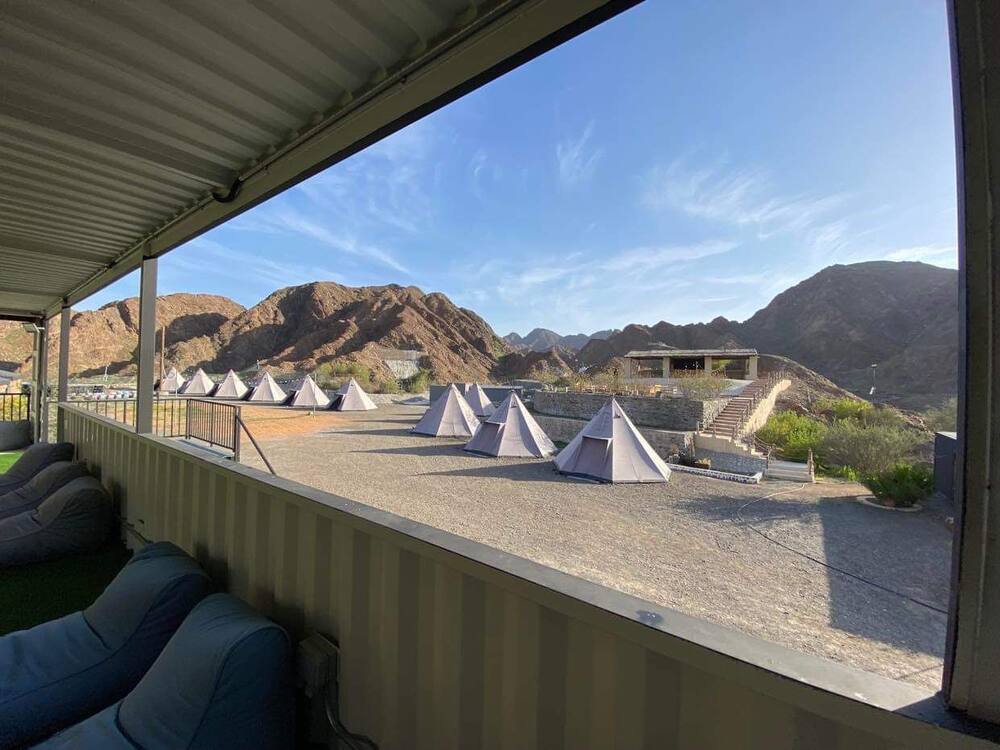
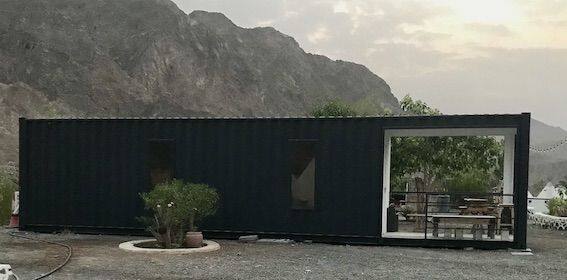
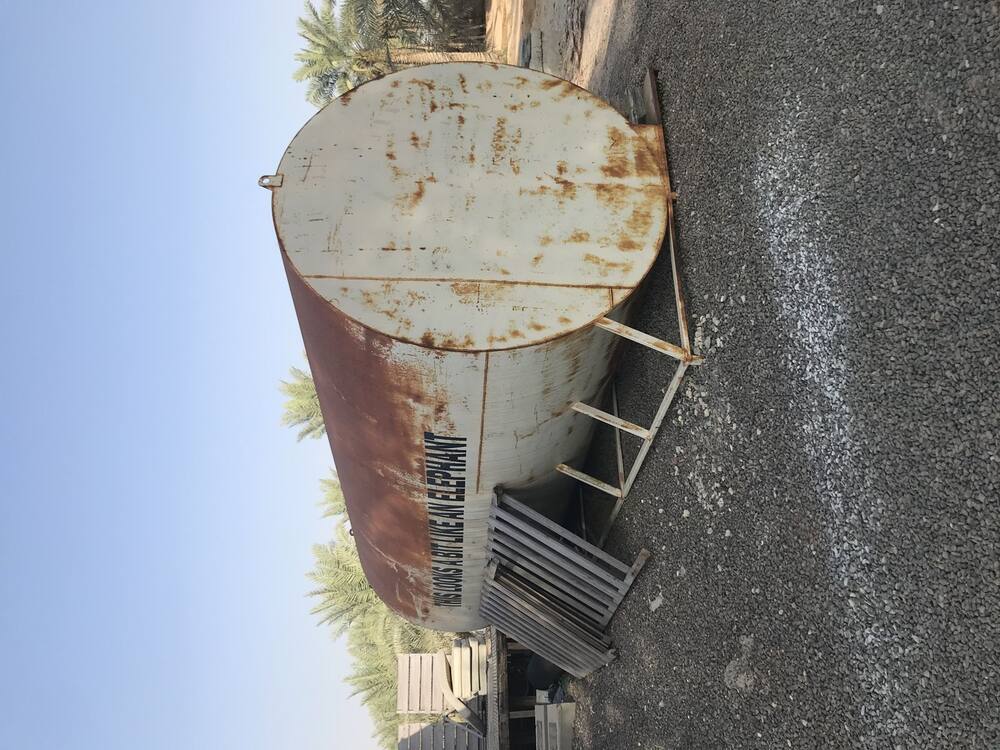
Live pipeline
Both are real and dated — but neither is contracted. Treat as demand evidence, not booked revenue.
LinkViva — Kayan Wellness Festival 2026
Fahid Island, Abu Dhabi · ~3 days, late Jan/Feb (tentative). Requirement: 20 glamping + 180 standard tents, common-area seating 100–200, showers/washrooms, a generator; decor optional. Proposal requested.